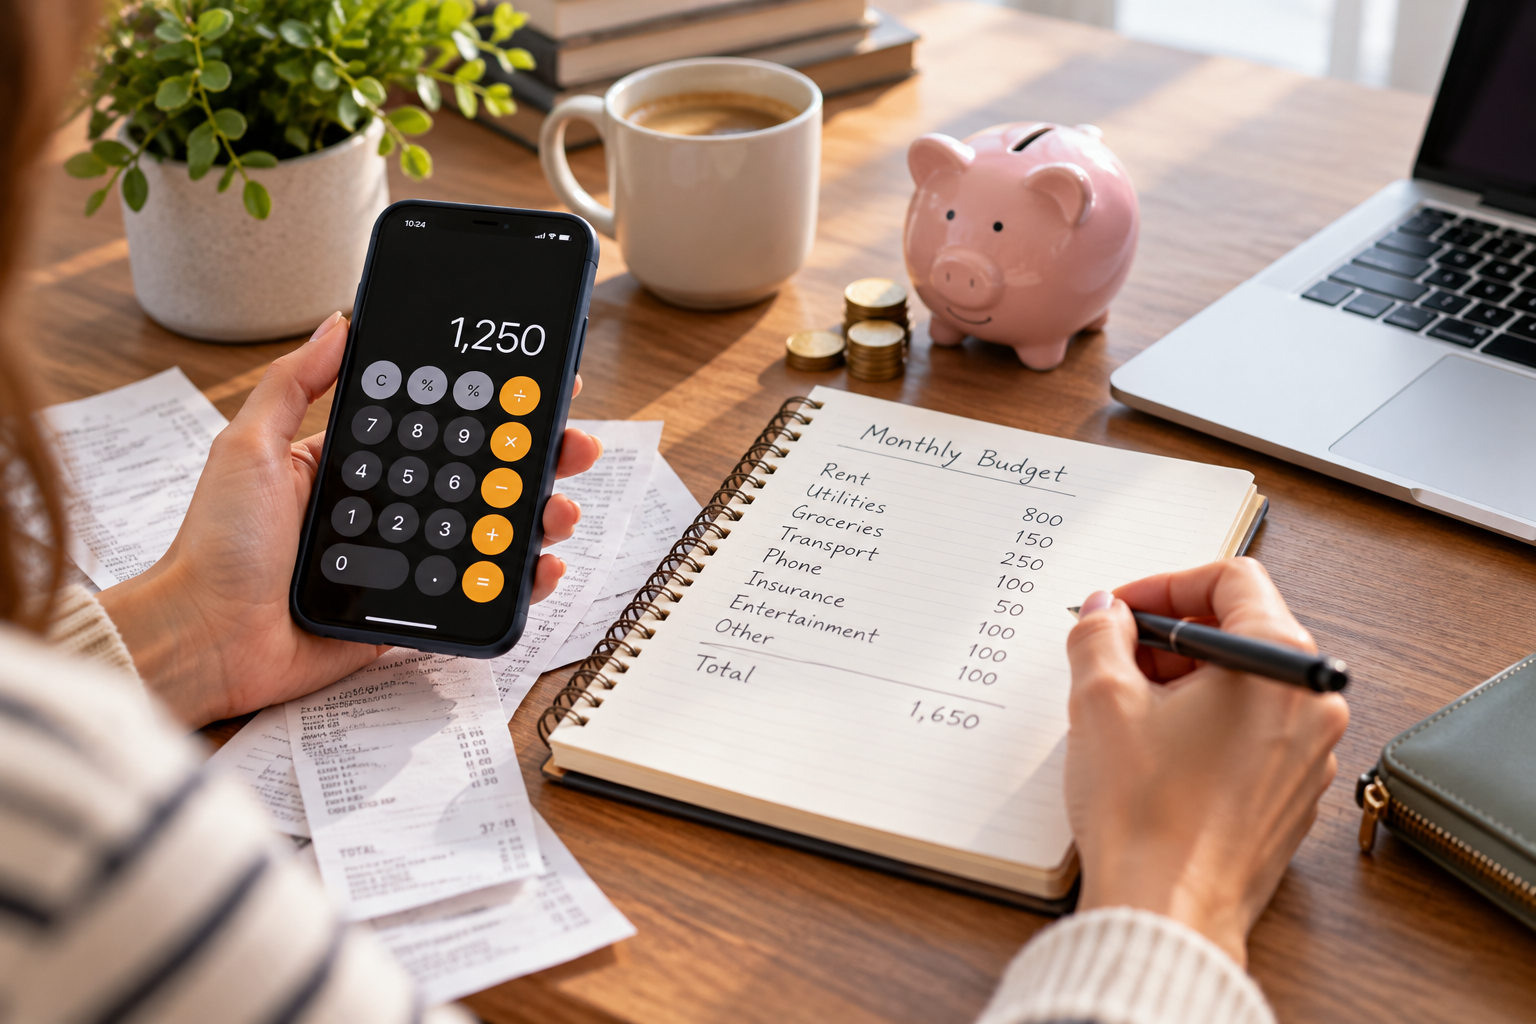
To budget money, start by calculating your monthly take-home income and reviewing what you actually spend. List your bills, regular expenses and less frequent costs, then decide how much money to assign to needs, wants, savings and debt payments. The best budget is not the one with the strictest rules. It is one that fits your real income and expenses and can change when your circumstances do.
A simple budgeting process looks like this:
- Calculate your monthly take-home income.
- Review your current spending.
- List regular and irregular expenses.
- Write down bills and due dates.
- Set financial priorities.
- Choose a budgeting method.
- Build the monthly plan.
- Track spending and adjust the plan.
Step 1. Calculate Your Monthly Take-Home Income
Start with the money you can realistically use each month.
For someone with a regular paycheck, that usually means net or take-home pay rather than gross salary. Your gross salary includes money that may never reach your checking account because of taxes and other deductions.
Include regular income from sources such as:
- paychecks;
- freelance or contract work;
- side work;
- benefits;
- child support, where applicable;
- other recurring income.
If your income changes from month to month, avoid building the budget around your best month. A more cautious approach is to use a lower recent month or a conservative average.
Fidelity similarly recommends working from actual monthly income and using the lower end of your normal range when earnings vary.
The purpose is to create a spending plan around money you can reasonably expect to receive rather than money you hope will arrive.
Step 2. Track What You Actually Spend
Before changing your spending, find out where your money goes now.
Review at least several weeks of:
- bank statements;
- credit card statements;
- receipts;
- subscriptions;
- cash purchases.
Sort expenses into broad categories such as:
- housing;
- utilities;
- groceries;
- transportation;
- insurance;
- healthcare;
- debt payments;
- childcare;
- subscriptions;
- eating out;
- entertainment;
- personal spending.
Do not start by inventing an ideal budget.
If you currently spend $700 a month on food, simply writing $400 into a spreadsheet does not create a workable plan. First understand why spending is at its current level. Then decide whether the category can realistically change.
The Consumer Financial Protection Bureau recommends getting a complete picture of income and actual spending before putting together a working budget.
Consumer Financial Protection Bureau — How to Create a Budget and Stick With It
Your first version of a budget can simply answer: Where is the money going now?
The next version can answer: What do I want to change?
Step 3. List Fixed, Variable and Irregular Expenses
Monthly expenses are easier to manage when you separate them by how predictable they are.
Fixed Expenses
These tend to stay the same or close to the same each month.
Examples include:
- rent or mortgage;
- loan payments;
- insurance;
- subscriptions;
- some childcare expenses.
Variable Expenses
These change from month to month.
Examples include:
- groceries;
- fuel;
- utilities;
- dining out;
- entertainment;
- household purchases.
Irregular Expenses
These are easy to forget because they do not happen every month.
Examples include:
- car repairs;
- annual insurance bills;
- school clothes;
- gifts;
- medical expenses;
- vacations;
- home repairs;
- seasonal expenses.
Irregular expenses are one of the main reasons a budget can look fine on paper and still fail in practice.
If you know an annual expense is coming, divide it into smaller monthly amounts. For example, a $600 annual cost can be treated as roughly $50 per month that you set aside in advance.
That turns an occasional large expense into something the monthly budget can anticipate.
Step 4. Write Down Your Bills and Due Dates
A budget needs to account for when money leaves your account, not only how much you spend during the month.
A simple bill calendar can look like this:
| Bill | Amount | Due date |
|---|---|---|
| Rent | $— | 1st |
| Insurance | $— | 5th |
| Phone | $— | 12th |
| Credit card | $— | 18th |
This becomes particularly useful when the total monthly income is technically enough to cover expenses, but the timing creates a shortage during a particular week.
For example, several large bills may fall before the second paycheck of the month.
Seeing income and due dates together can help you decide when to transfer money, when to limit flexible spending and whether changing a bill’s due date is worth asking about.
Step 5. Separate Needs From Wants
A useful budget distinguishes necessary expenses from flexible ones without treating every enjoyable purchase as a mistake.
Needs
These generally include expenses required for daily life and basic financial obligations:
- housing;
- essential utilities;
- groceries;
- necessary transportation;
- insurance;
- essential healthcare;
- minimum required debt payments.
Wants
These are expenses that improve comfort or enjoyment but usually have more flexibility:
- dining out;
- entertainment;
- optional subscriptions;
- hobbies;
- nonessential shopping;
- travel.
The line is not always identical for every household. Transportation that is optional for one person may be essential for someone who needs a car to reach work.
More importantly, a budget does not have to eliminate wants.
A plan that allows no room for flexible spending may look efficient in a spreadsheet but be difficult to maintain for months at a time.
Step 6. Choose a Budgeting Method
There is no single budgeting method that works best for everyone. Choose one that gives you enough structure without making money management unnecessarily complicated.
The 50/30/20 Budget
A common framework divides take-home income approximately into:
- 50% for needs
- 30% for wants
- 20% for savings and additional debt repayment
These percentages are a guideline, not a requirement.
Housing, childcare, healthcare or transportation costs may push essential spending well above 50% for some households. Others may be able to save considerably more than 20%.
The value of the framework is that it gives you a quick way to look at the balance between major categories.
Zero-Based Budgeting
A zero-based budget assigns a purpose to all available income.
Money can be assigned to:
- bills;
- everyday spending;
- savings;
- debt payments;
- irregular future expenses.
When the plan is complete, income minus all planned uses equals zero.
That zero exists in the plan. It does not mean you should empty your bank account.
NerdWallet includes both 50/30/20 and zero-based budgeting among the systems people can use depending on how much structure they want.
NerdWallet — How to Make a Budget
A Simple Spending Plan
Beginners do not necessarily need a named method.
You can use:
income → essential bills → savings and goals → flexible spending
If that is easy to understand and you consistently use it, it is a valid budgeting system.
Step 7. Build Your Monthly Budget
Now combine the information into one monthly plan.
| Category | Planned |
|---|---|
| Monthly take-home income | $— |
| Housing | $— |
| Utilities | $— |
| Food | $— |
| Transportation | $— |
| Insurance / healthcare | $— |
| Minimum debt payments | $— |
| Savings | $— |
| Wants / flexible spending | $— |
| Irregular expense funds | $— |
| Money left | $— |
The central rule is simple:
planned spending + planned savings should fit within available income.
If your expenses are higher than your income, look at the categories separately rather than making a vague promise to “spend less.”
Review:
- optional subscriptions;
- dining and entertainment;
- shopping;
- other flexible spending;
- recurring bills that may be negotiable or replaceable;
- categories where spending has gradually increased.
Do not remove savings automatically just to make the spreadsheet balance. Savings can be part of the plan just like bills and spending.
If essential expenses alone are consistently higher than income, however, the problem goes beyond normal budget optimization and may require a different approach to bills, assistance or income.
How to Make a Budget Actually Work
Creating the spreadsheet is the easy part. The budget only becomes useful when you compare it with what happens during the month.
Check It Regularly
You do not need to monitor every purchase obsessively.
A short check once a week may be enough to see:
- how much has been spent;
- which categories are close to their limits;
- which bills are coming next;
- whether anything unexpected has changed the plan.
Track Spending Before the Month Is Over
Finding out on the last day of the month that a category is $300 over budget does not leave much room to respond.
Checking while the month is still underway gives you choices.
Automate Predictable Parts
Automatic transfers can simplify savings and recurring bills when your cash flow is predictable enough to support them.
This does not mean everything needs to be automated. The goal is simply to reduce the number of decisions that have to be remembered manually.
Fix Unrealistic Categories
If grocery spending exceeds the target every month, entering the same target again next month will not solve the mismatch.
Either the spending behavior needs to change or the budget number needs to become more realistic.
A useful budget should describe the life you are actually living while helping you change the parts you deliberately want to change.
Update It When Life Changes
Review the budget when there is a meaningful change in:
- income;
- rent or mortgage;
- childcare;
- insurance;
- debt payments;
- family circumstances;
- recurring expenses.
The first budget is not supposed to remain unchanged forever.
Simple Budgeting Tips for Families
A family budget uses the same basic process, but more irregular expenses tend to appear.
Remember categories such as:
- childcare;
- school expenses;
- groceries;
- transportation;
- healthcare;
- children’s activities;
- clothing;
- birthdays;
- holidays;
- family travel.
It can help for both adults to have access to one shared view of the major household bills and upcoming expenses.
You can also agree in advance on which categories can be spent independently and which larger purchases should be discussed first.
Seasonal costs deserve special attention. Back-to-school purchases, holidays and annual activities may not appear in an ordinary month but can still be planned for gradually.
There is no universal percentage that every family should spend on childcare, food or other categories. A useful family budget has to reflect the actual household.
What If Your Budget Does Not Balance?
If planned expenses are higher than income, first make sure the numbers are accurate.
Then work through the problem in order:
- Separate essential expenses from discretionary spending.
- Review subscriptions and recurring charges.
- Look at flexible categories.
- Check whether bill timing or payment arrangements can be changed.
- Consider realistic ways to increase available income where possible.
Do not try to force a 50/30/20 framework onto a situation where essential expenses already consume nearly all available income.
A standard beginner budget helps organize money. It cannot by itself solve a situation where there is not enough income to cover basic obligations.
A useful budget starts with your real numbers rather than an ideal version of how you think you should spend. Track what comes in, account for where it actually goes and choose a simple system for assigning the money available. Review the plan regularly and change it when income, bills or priorities change instead of treating the first version as permanent.